


Article
Why I Wait at Cyclical Bottoms Instead of Chasing Growth

Stocks and equity indices that receive the most attention in the media are showing increasingly lower returns when measured against the actual revenues or profits of the underlying companies. This discrepancy led me to start looking elsewhere, toward opportunities that are talked about far less.
Sector cycles and mean reversion
Over time, I have been paying more and more attention to sectors that follow a certain internal logic and exhibit relatively recurring cycles. Cycles that are visible both in market behaviour and in the development of accounting data. In some cyclical sectors, stock prices can fall all the way down to book value, or very close to it. At such moments, the balance between risk and potential return begins to change for me. Not because I expect a quick rebound, but because at these levels further declines often become less likely. What tends to be more probable is either a prolonged period of stagnation or a turning of the cycle. This tendency of prices to move back toward a long-term average after an extreme is what is generally called mean reversion. To be clear: I am referring here to the book value of companies across an entire sector. I am interested in the sector as a whole, not in individual companies, as company-specific outcomes are usually far less predictable.
I therefore focus on the sector as a whole and its recurring cycles. Moving capital between sectors as their cycles turn is what is often described as sector rotation. Time plays a crucial role in this approach. Waiting for a cycle to turn, watching prices move sideways for months or even years, is ultimately a matter of discipline and patience. On the surface, nothing particularly interesting seems to be happening, and that is precisely what many people find most difficult. Paradoxically, however, this phase is psychologically easier for me than constantly moving from one “growth opportunity” to another.
Concentration, patience, and contrarian timing
Before I began to observe these types of situations more systematically, I tended to diversify more broadly across different growth sectors. Today, when I see a logically cyclical opportunity and prices are hovering around book value, I am more inclined to concentrate a larger portion of my portfolio. Concentrating capital in sectors that most people are avoiding is, in essence, a contrarian and value investing stance rather than a growth one.
Some cyclical sectors can linger near book value for years. From a price perspective, it is therefore usually not too difficult to roughly identify a bottom. On the other hand, I never aim to predict tops. Sometimes a cycle results in a fifty-percent increase, at other times in several multiples. My goal is not to catch the maximum, but to exit with a reasonable profit.
Price-to-book versus price-to-earnings
When I compare this approach to investing in very expensive growth sectors from the perspective of price-to-earnings ratios (P/E), I sleep more peacefully waiting at a cyclical bottom than entering something trading at historically high valuations. Buying at historical lows in price-to-book ratios (P/B) is mentally easier for me than buying amid widespread euphoria (P/E highs).
I do not want to talk about specific sectors or instruments. I do not view this blog as investment advice, nor is it intended to be one. I do not recommend specific investments; rather, I write about how I think about markets, what strategy and tactics I use, and why they make sense to me. I am saving this text here primarily as a record of my own thinking.
Continuation: The Risk–Reward Principle I Did not Explain Clearly in My Article on Cyclical Opportunities
Disclaimer
This article is intended for informational and educational purposes only. It does not constitute financial advice, a recommendation to buy or sell any securities, or a guarantee of future market performance. The views expressed are solely those of the author, who may also be an investor. Investing in financial markets involves risk, and each reader should make their own decisions independently and, if necessary, consult with a licensed professional.
Summary
Common questions on this article's topic
What are cyclical stocks?
What is the price-to-book ratio and why does it matter for cyclical investing?
How does cyclical investing differ from growth investing?
How long can a cyclical bottom last?
Should investors try to time the top of a cycle?
Is cyclical investing suitable for everyone?
What is mean reversion in investing?
What is sector rotation?
What is contrarian investing?
If you have any thoughts, questions, or feedback, feel free to drop me a message at mail@richardgolian.com.
 LinkedIn


Related articles
A very good question. More and more, I feel that I am chasing things that do not make me happy at all and that I do not need to be happy at all. So why am I chasing them?
In April, in the first part of this series, I wrote about an AI prediction system I had started building on my own machine. At the time the software was a few hours old and the prediction record was empty. The record since then has shown one thing: the system does not yet understand the market it is being asked to forecast. It can pull macro context, book value, earnings. But it cannot put those together into something that helps it understand the price.
Prague, 13 May 2026. On my way to work I started thinking about something that stayed with me for days. If most routine work on a computer disappears in the next ten years, and a large share of repetitive manual work disappears with it, what happens to the flow of money? Who pays whom for what? Which economic layers will exist, how large will they be, and what relationships will run between them? This is the six-layer map I sketched as an answer.
More articles
Are you a content creator playing by the rules of YouTube, Instagram or Google? Are you a small business owner whose business model depends on how often Amazon recommends you, how expensive Facebook ad impressions will be or how expensive Google Ads clicks will be? If all or most of your contact with your audience or customers depends on a big platform showing you to them, you are not in a strong position.
The development of artificial intelligence changes how we look at which paths in life make sense. Which studies and which profession to choose.
It was Thursday, 31 March 2022, when I handed over the last of my responsibilities to my colleagues, closed my laptop and went to the library. I left my job for several months and immersed myself in philosophy. And I am immensely grateful for it. Today I am, like most people, on a merry-go-round, and it is hard for me to stop and think about the fundamental questions of my own life.
It was September 2023. My life, my work, everything was completely different from now. It was simpler. I owned almost nothing. I needed to film an advert, I went up to a floor inside the company where the product I needed for that advert was, and there I noticed her for the first time. She laughs at me when I describe it like this, but at that moment the universe told me, that is her.
How and why I am gradually leaving social media and the big platforms. When I read that Meta is testing a new way to charge for organic posts that link outside its platform, it confirms how right I was to become steadily less dependent on the big platforms and on social media. It does not mean I have left them completely. It means that whether or not I stay in touch with my readers depends on them less and less, and today almost not at all.
One of my family members described a firm that has its data in several different tools, and its employees still join it by hand, in spreadsheets. That is the ordinary state of firms. When somebody tells such people not to do it by hand and to use AI, they will not understand. Most firms do not even have the basic connectors between the tools they use. These firms need help with AI transformation.
The same task, two models. Fable 5 against Opus 4.8. On paper Fable is the better model, with a larger context and stronger specs. And still it lost. Opus handled the task with a single round of checking for 721,000 tokens, while Fable needed nine rounds and burnt through 2.78 million tokens. The difference was not in the model, but in how I set the task. And I know it, because I measured it.
A few weeks ago I installed a small local AI model on my laptop that watches a live camera feed. I turned the webcam on in the dark, and in near total darkness it recognised me and the objects in the room. That such things exist, I have known for a long time. What opened my eyes was the accessibility. I installed it in one prompt, free, and it runs entirely on my machine, sending data nowhere.
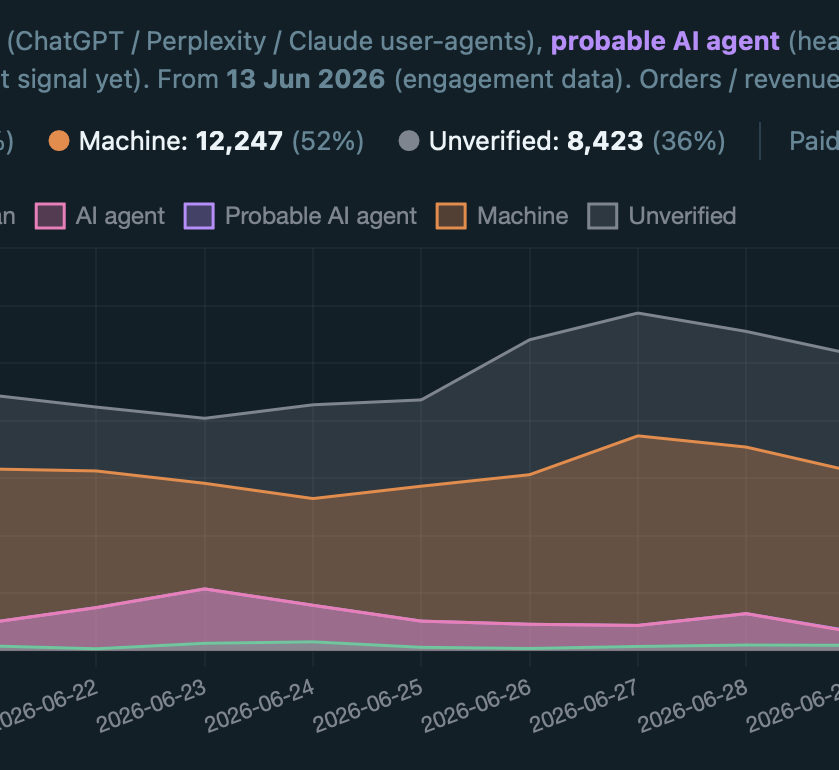
I once wrote about building my own privacy-friendly analytics tool. It had bot detection from the first version, yet it was not enough. Direct visits took a strangely high share of my traffic. When someone claims that 20% of their visits are bots and 80% are humans, I used to think the same. Today I would say the opposite ratio is closer to the truth. This is how I got there.
I have Heidegger and my notebook beside me. I am asking where all of this is heading, where artificial intelligence is taking us.
Four days in Catalonia. No computer, no AI, almost no social media. I bought this notebook so that I could write down what I would think about, and what I would come across and learn on the trip.